
Stage 04 - Preparing for Retirement
After years of hard work, with the family business now well established, Jia Wen and her husband are beginning to think about retirement.
They hope to slow down, travel occasionally and spend more time with their family.
But one question keeps coming back: If they stop working, will they have enough money coming in every month to support the life they want?
Meet Jia Wen — Retirement Is Getting Closer
Jia Wen is now 54, and her husband is 56.
Their family business is doing reasonably well after many years of hard work.
Years ago, Jia Wen faced a difficult decision about whether to leave her stable job and join her husband’s business.
After carefully considering their family finances and discussing her role, salary and benefits, she eventually decided to join him.
Over the years, they worked together to support the business while raising their two children.
Their daughter, now 25, is building her own career, while their 22-year-old son is beginning to explore a role in the family business.
With their children growing more independent, Jia Wen and her husband finally have more time to think about their own future.
They hope to slow down, travel occasionally and enjoy more time together.
But as retirement gets closer, Jia Wen begins to wonder:
“We’ve worked so hard to build the business. But are we financially ready to stop working?”
A Conversation About Their Retirement
One evening, Jia Wen and her husband sit down to talk about their retirement plans.
“We’ve worked hard all these years,” her husband says. “Maybe in a few more years, we can slow down and let our son take on more responsibility in the business.”
Jia Wen smiles. “That would be nice. We could travel more and spend time doing things we enjoy.”
Then she asks, “But when we stop working, where will our monthly income come from?”
Her husband replies, “We still have the business. If our son eventually takes over, perhaps it can continue providing us with income. Or we could sell it one day.”
Jia Wen thinks for a moment.
“Our son is still learning. What if he needs more time, or decides the business isn’t right for him? And what if we can’t sell the business when we want to, or at the price we expect?”
Her husband agrees that they need to understand their options before making any decisions.
They also realise that their daughter’s future is taking a different direction. She has chosen her own career, while their son may eventually become involved in managing the business.
For now, they agree not to rush their children into decisions about the company’s future.
They want to understand how their retirement could be funded, whether the business continues under their son or their plans change.
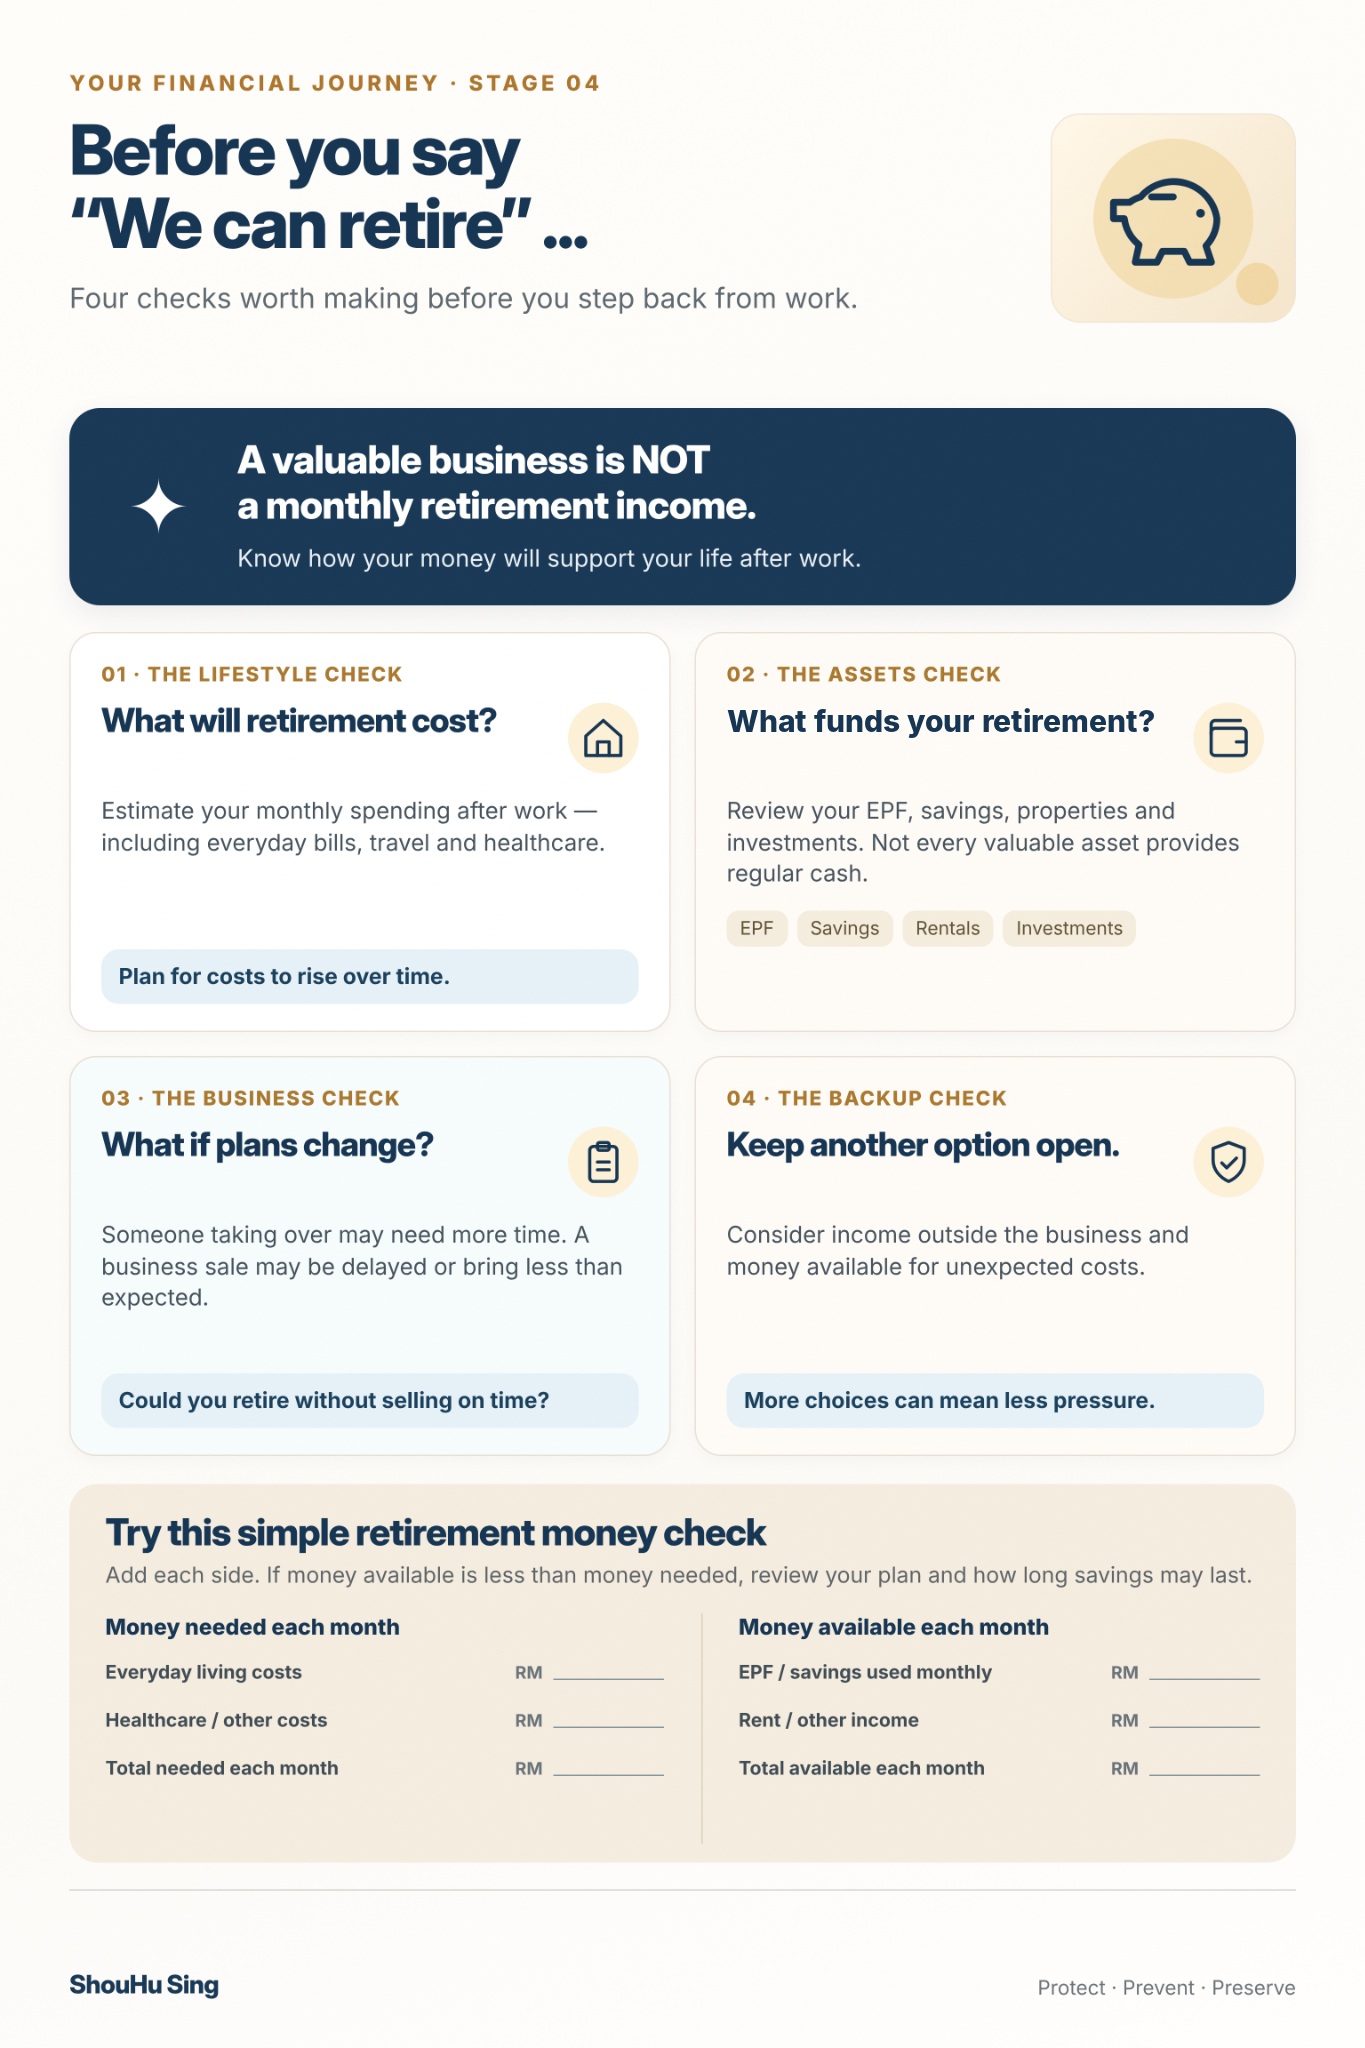
Having a valuable business and having enough money coming in every month after retirement are two different things.
Something Else They Had Overlooked
For years, the family business has been their main source of income.
Along the way, Jia Wen and her husband have also built up their wealth through properties, EPF, unit trusts, other investments and savings.
They had started setting aside money for retirement when their children were younger, and continued making adjustments as their circumstances changed.
On paper, they seem to be doing quite well.
But Jia Wen begins to wonder:
“When we stop working, which of these assets will actually provide the money we need every month?”
Their properties may be valuable, but not all of them generate rental income. Their investments may grow over time, but their value can also change.
And selling an asset whenever they need money may not always be practical.
They realise that having savings and investments is only part of retirement preparation. They also need to understand how those assets could provide income throughout their retirement years.
They decide to look more closely at what they already own, which assets could provide regular income, and whether their available money would be enough to support the retirement lifestyle they want.
Before deciding when to retire, they want to understand what their money can realistically do for them.
What I Wish I Knew Before Planning My Retirement
1. A successful business doesn’t automatically mean a comfortable retirement.
Our business may be doing well today, but we need to know where our monthly income will come from when we stop working.
2. Having properties and investments doesn’t mean we have enough retirement income.
We should check which assets can provide regular income, which may need to be sold, and whether the money will last.
3. Retirement expenses don’t stop when our salary stops.
Daily living expenses, medical costs and occasional travel still need money. We should also prepare for rising costs as we grow older.
4. Our retirement shouldn’t depend entirely on our children taking over the business.
Our son may need more time to learn, or he may choose a different path. We need a retirement plan that gives us choices, even if our business plans change.
5. We don’t have to wait until we stop working to prepare for retirement.
We can start by reviewing what we already own, estimating how much we need each month, and gradually making adjustments while we still have an income.
A Quick Check for Yourself
How much monthly income will I need when I retire?
Can my savings and investments support my retirement lifestyle?
Can I afford to retire without selling my business?
Have I prepared for rising living and medical costs?
What is my backup plan if retirement doesn’t go as expected?
THE JOURNEY CONTINUES
Retirement Is Not Just About Stopping Work. It's About Having Choices.
Jia Wen and her husband realise that owning a successful business, properties and investments doesn’t automatically mean they are ready to retire.
They begin reviewing what they already have, where their future monthly income could come from, and what might happen if their business plans change.
They haven’t decided exactly when to retire. But they now understand why having money available outside the business matters.
Retirement doesn’t have to depend on selling the business at the right time or at the right price.
As they get closer to retirement, another chapter begins — learning how to gradually step back from work while keeping their family’s finances on track.
Wondering Whether You Can Afford the Retirement You Want?
Before making big decisions, it’s worth understanding how your savings, investments, properties and business fit into your retirement plans.
We can review what you already have, identify what may need attention, and discuss which steps make sense for your situation.
Michelle Wan · Registered Financial Planner in Melaka